Can I Use Homeowners Insurance to Pay for a Roof Replacement After Storm Damage?

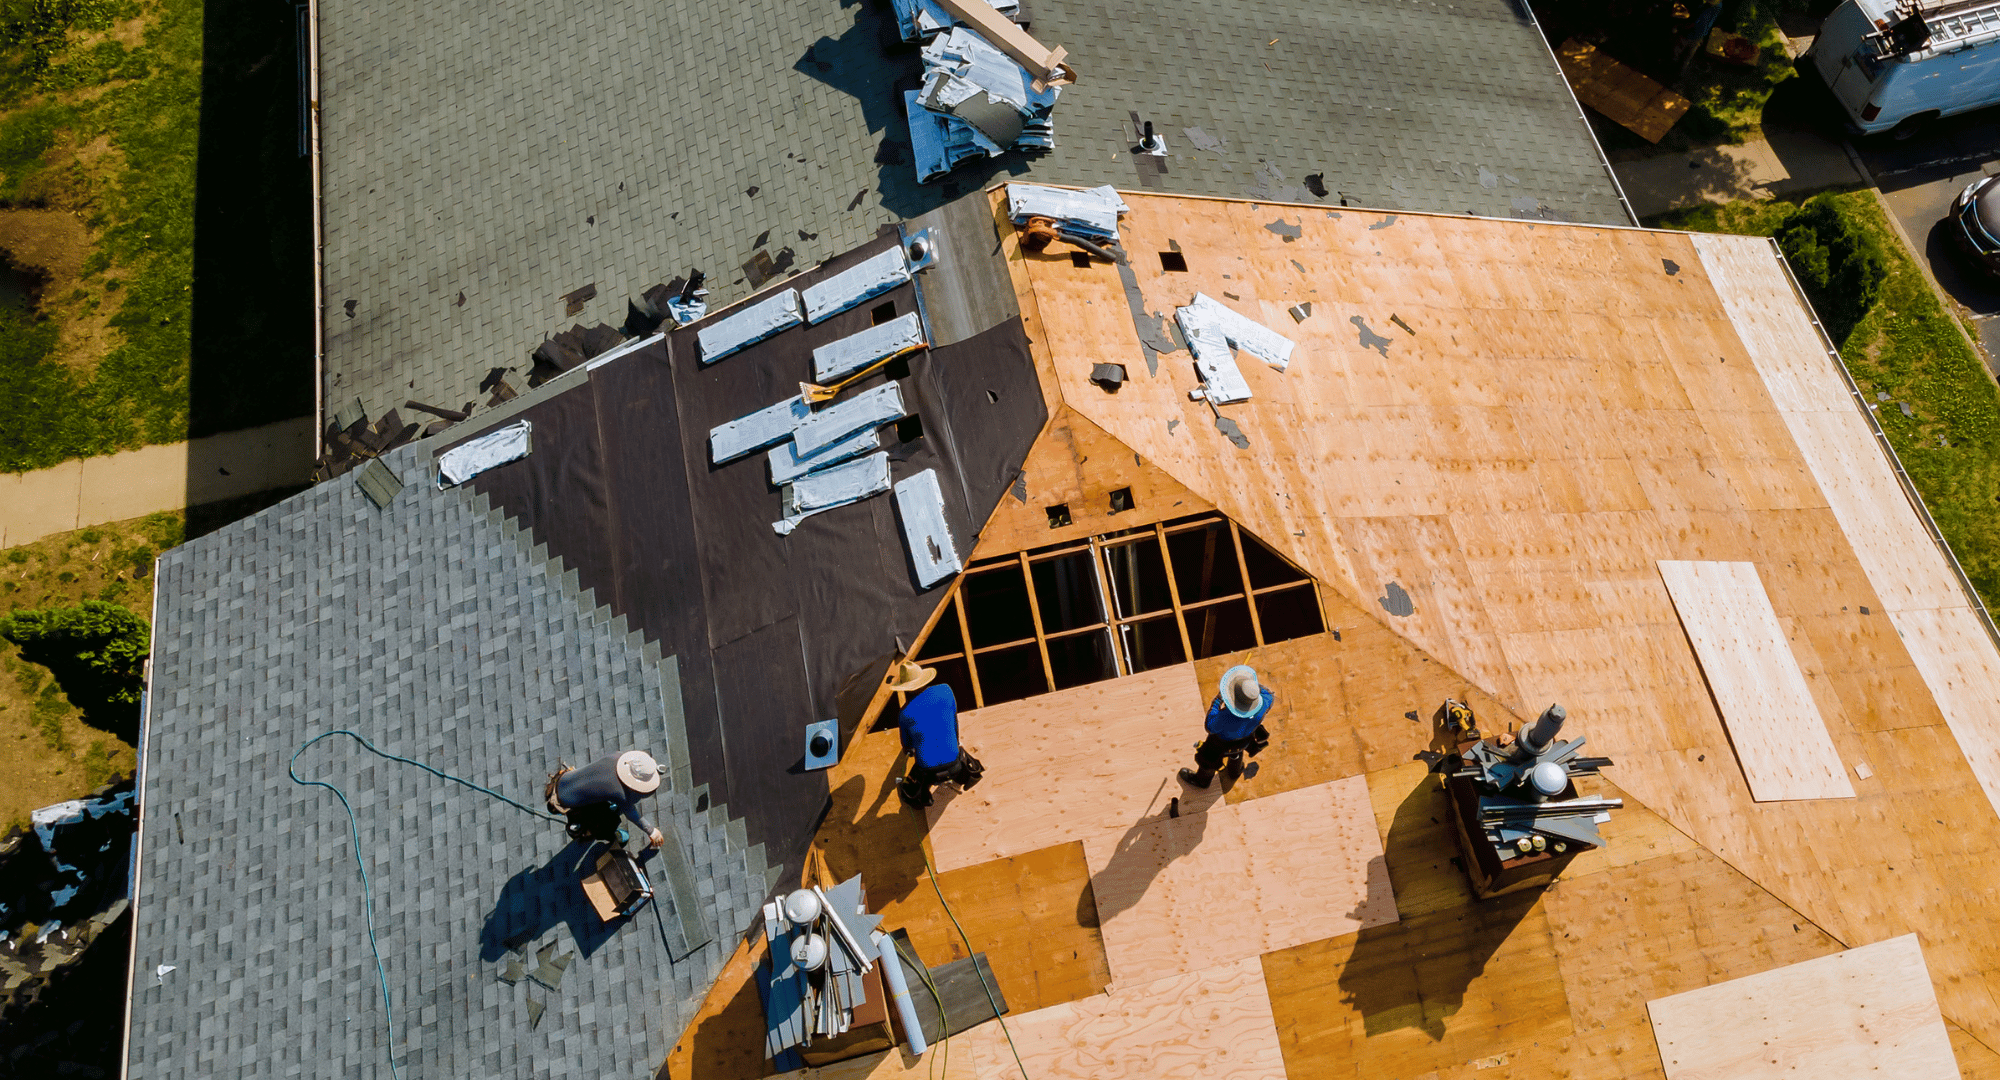
Yes, homeowners insurance often covers roof replacement when storm damage is the cause. Whether it pays for the full replacement depends on your policy type, your roof's age, and the extent of the damage. The best first step is a professional inspection to document the damage before you file a claim.
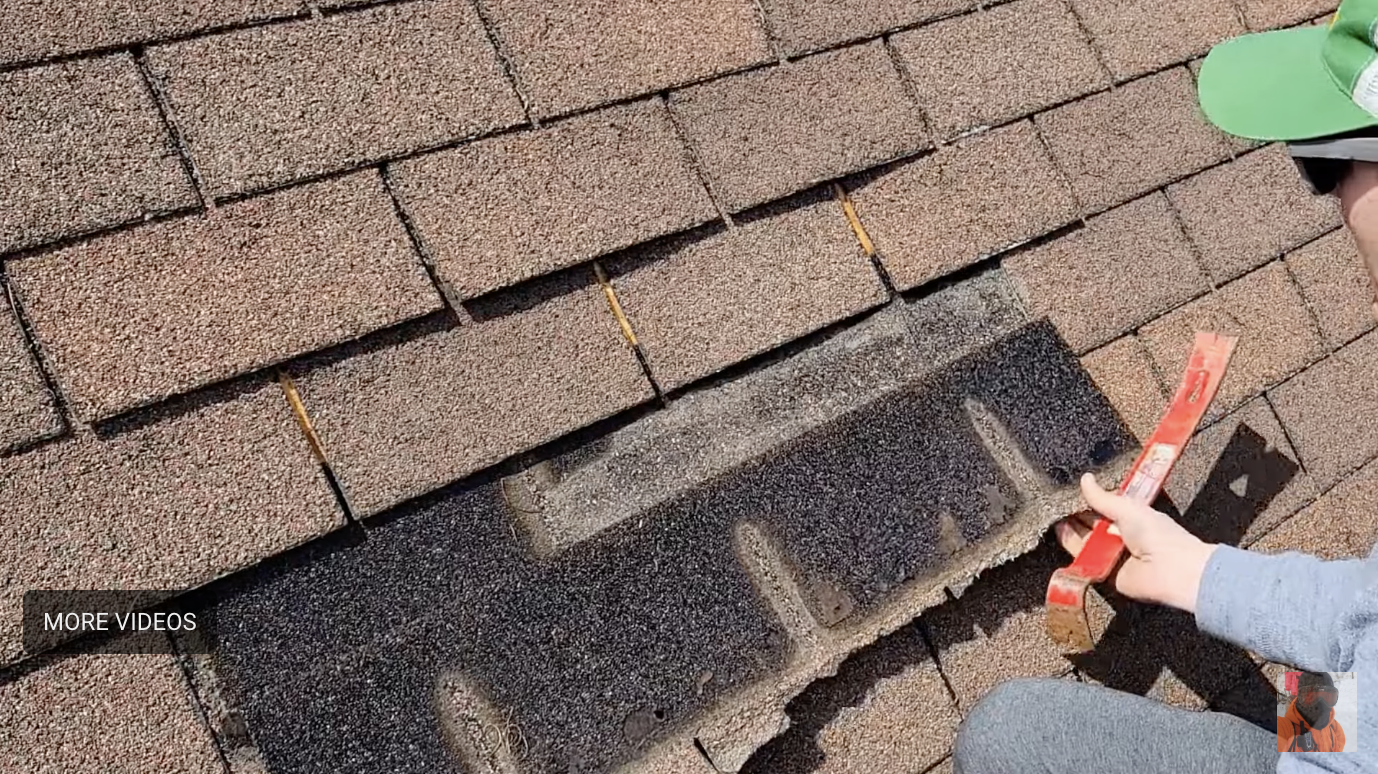
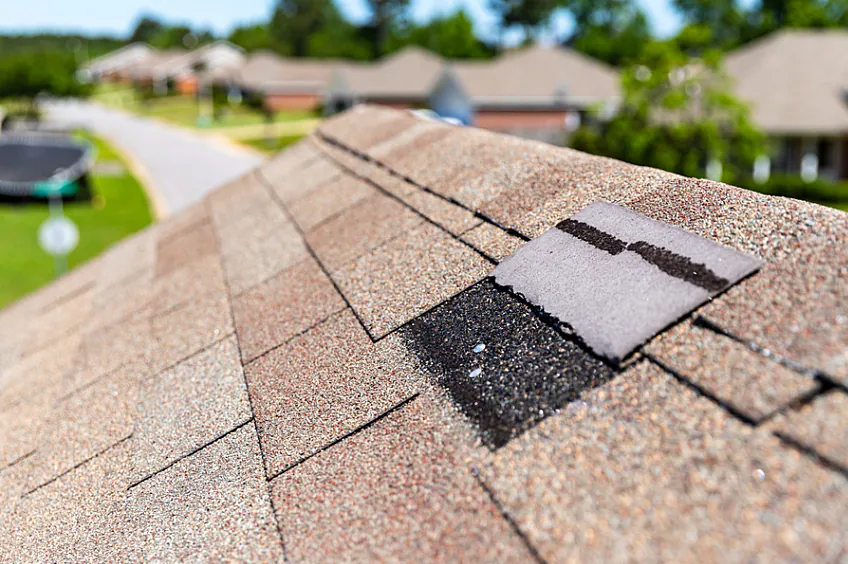
A homeowner recently called us after noticing missing shingles following a recent storm. Their roof was about 16 years old, they had a minor leak, and neighbors had already gone through the insurance process successfully. They wanted to know: can we do the same thing? The answer is often yes, and we walk families through this regularly.
At Douglas Roofing, we help homeowners understand what to expect before, during, and after the insurance process. Here is how it works.
Most standard homeowners insurance policies cover sudden, storm-related damage, including wind, hail, and falling debris. What they typically do not cover is wear and tear or damage from neglect. This distinction matters a lot when you file a claim.
If your roof is older and has missing shingles, your insurer will look at whether the damage was caused by the storm or by age. A well-documented inspection report helps establish that connection. That is exactly why getting a professional out before you call your insurer is the right move.
The process generally follows a few clear steps, and a good roofing contractor will guide you through all of them. Here is what you can typically expect:
Your roofing contractor should be comfortable meeting with the adjuster and advocating on your behalf. We do this regularly for homeowners across Northern Virginia.
Yes, roof age can significantly affect your payout. Some policies cover replacement cost value, meaning they pay what it costs to put on a brand-new roof. Others cover actual cash value, which factors in depreciation based on age.
If your roof is 15 or 16 years old, an actual cash value policy may only cover a portion of the cost. Reviewing your policy before you file helps set realistic expectations. Our team can help you understand what the inspection findings might mean for your specific situation. Learn more about what goes into a full roof replacement and what we look at during an assessment.
If a past repair failed and the damage has returned, that history actually supports your case for a full replacement. It shows the roof has a documented problem that a patch could not resolve. Insurers take this into account, especially when combined with storm damage on an aging roof.
We have seen this situation many times. A local contractor does a quick fix, a couple of years pass, and the homeowner is back to square one. At that point, a full replacement is often the smarter and more cost-effective path. Our experienced team can assess whether repair or full replacement makes more sense given your roof's current condition.
No. In fact, we recommend getting a professional inspection first. The documentation from that inspection is exactly what your insurer needs to evaluate your claim. Filing without it can slow the process down.
It depends on your insurer and your claims history. This is a question best directed to your insurance agent. What we can tell you is that many homeowners in our area have successfully filed claims without major rate increases, especially when the damage is clearly storm-related.
Yes. We are experienced working alongside insurance adjusters and can communicate on your behalf during the assessment. We make sure the scope of damage is accurately represented so nothing gets overlooked.
If you are in Herndon, VA or the surrounding Northern Virginia area and your roof took a hit in a recent storm, do not wait. The longer damage sits, the more complicated the claim can become. Our inspections are free, and we will give you a straight answer about what we see.
Contact us today to schedule your free roof inspection and find out if an insurance claim makes sense for your situation.